Insured for What You Paid? How a Coinsurance Penalty Shrinks a Partial Claim
The 80 percent replacement cost rule decides how much of a partial loss gets paid, and first-time policyholders usually meet it at renewal rather than at purchase.
Hector Villanueva1,085 words
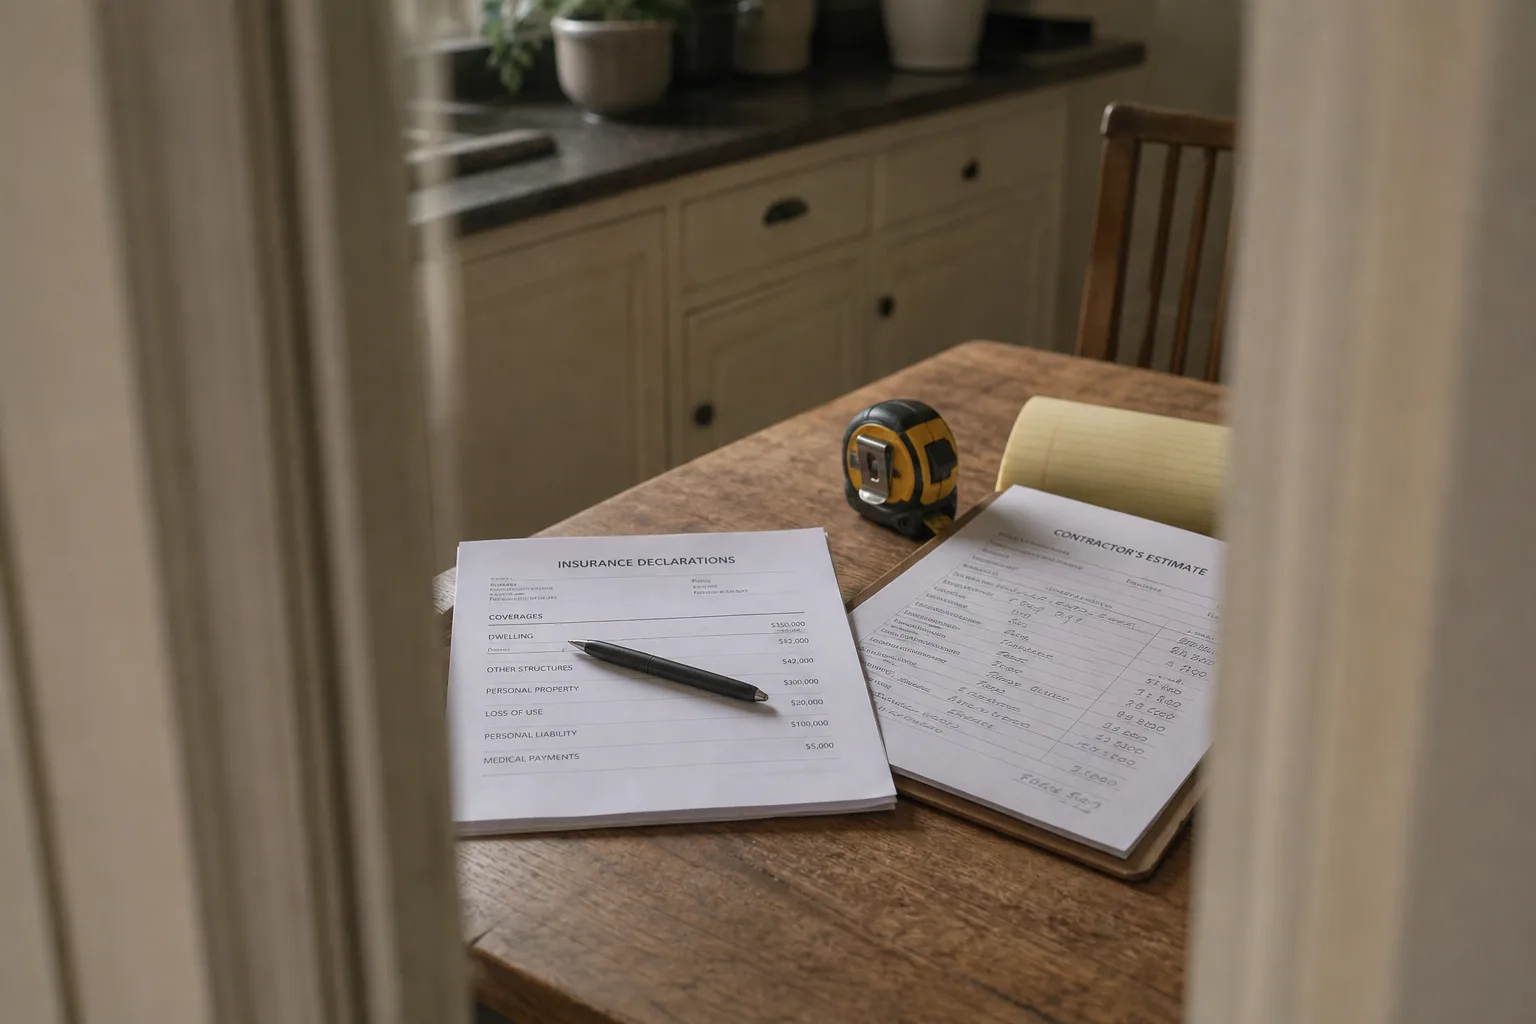
The dwelling limit on a homeowners policy is not the purchase price, not the appraised value, and not the property tax assessment. It is an estimate of what a builder would charge to put the same structure back on the same lot at today's labor and material prices, which is a different question from what a buyer would pay for the house and the land underneath it. First-time policyholders often set that limit by reflex, matching it to the mortgage or the sale price, and the mismatch sits quietly on the declarations page until a partial loss arrives and the arithmetic surfaces.
Where the shortfall comes from, and why it rarely announces itself
Three things push a limit below replacement cost, and none of them require anyone to be careless. Construction costs move independently of home values, so a stretch of rising lumber, drywall, and framing labor prices can open a gap while the market value of the house sits still. Renovations add square footage and finish quality that were never reported to the carrier. And the original estimate, generated from a square footage model at the time of binding, may have missed a finished basement, a detached garage, or the plaster and millwork that a rebuild would have to reproduce. The limit stays where it was. The cost of the work does not.
What makes this hard to spot is that total losses are rare and partial losses are common. A kitchen fire, a burst supply line, a tree through the roof: these produce repair bills far below the dwelling limit, so a homeowner looking at a policy with a limit of several hundred thousand dollars reasonably assumes a forty thousand dollar repair is comfortably inside it. The replacement cost condition does not work that way. It measures your limit against the full cost to rebuild the entire structure, then applies the result to the partial claim.
The eighty percent condition and the arithmetic it triggers
Most homeowners policies written on a replacement cost basis carry an insurance-to-value requirement, commonly eighty percent. Carry a limit of at least eighty percent of the full replacement cost at the time of loss, and a covered partial claim is settled at replacement cost, less the deductible. Fall below it, and the settlement is reduced in proportion to how far short you are. In commercial property this is called a coinsurance clause, and the same mechanism appears in the National Flood Insurance Program, which the Federal Emergency Management Agency is responsible for administering. The language varies. The structure does not.
The shape of the calculation is worth working through once with illustrative numbers. Suppose a rebuild would cost five hundred thousand dollars, so the eighty percent threshold is four hundred thousand, and the policy carries a limit of three hundred thousand. The ratio of what you carried to what you should have carried is three-quarters. A one hundred thousand dollar repair is then settled at roughly seventy-five thousand before the deductible comes out, and the remaining twenty-five thousand is yours. Nothing was excluded. The loss was covered in full, and the payment was reduced by a condition printed in the policy.
The endorsements that hold the number up between renewals
Carriers know limits drift, and the standard tools for holding them in place are all endorsements you can confirm in writing. An inflation guard provision raises the dwelling limit automatically at each renewal, indexed to construction cost movement rather than to home prices, which is the reason the increase sometimes runs ahead of your neighborhood's sale comparables. Extended replacement cost adds a stated cushion above the limit, often expressed as an additional percentage, so a moderate underestimate does not become a penalty. Guaranteed replacement cost goes further and commits the carrier to the actual cost of rebuilding, subject to the policy's own conditions and availability in your state.
Ordinance or law coverage belongs in the same conversation, because it addresses a different gap with the same result. When a damaged house is repaired, current building code applies to the work, which can mean new wiring, updated egress windows, or a hurricane-rated roof deck that the original structure never had. A base policy pays to restore what was there. Ordinance or law coverage pays the incremental cost of complying with code, and on an older house it is frequently the difference between a repair that finishes and a repair that stalls at the inspection.
Whether the extra premium earns its place on the bill
Raising a dwelling limit is one of the few insurance changes where the payback is calculable rather than speculative. Premium is broadly proportional to the limit, so moving a limit up by a fifth moves the dwelling portion of the premium by something in that neighborhood, on a base that is itself only part of the total bill once liability, personal property, and fees are counted. Set that annual increase against the exposure it removes, which in the illustration above was twenty-five thousand dollars on a single mid-sized claim. The comparison usually resolves quickly, and it resolves the same way each renewal.
The other half of the calculation is the deductible, and the two should be decided together rather than separately. A higher deductible lowers premium and is a rational trade for a household with reserves, but it only works if the limit above it is sound, because a proportional reduction and a large deductible stack on the same claim. Fixing the limit first, then choosing a deductible you could write a check for tomorrow, produces a policy where the retained risk is a number you picked deliberately.
When to check, and what to send
The check is quick once you know what it involves. Ask the carrier or agent for the replacement cost estimate behind your current limit, not the limit alone, and read the inputs: square footage, foundation type, roof covering, number of bathrooms, finish grade. Report finished basements, added rooms, upgraded kitchens, and any structure the model would not know about. A contractor's estimate or a local builder's per-square-foot figure gives you a second reference point. Do this before a loss, in writing, and the number on the declarations page becomes something you chose instead of something you inherited.
A first policy is usually bought under a closing deadline, with the lender waiting and the limit set by whatever the system proposed. The first renewal is the natural moment to correct it, and the correction takes one phone call and one document.